The Myth of the One-Size-Fits-All Benefit
A workplace benefit can look valuable on paper but miss your needs. Learn what to ask about access, flexibility, costs, and fit before relying on it.
The most common mistake with a workplace benefit is assuming its name tells you whether it will help. A benefit can sound generous yet cost you time or peace of mind if you plan around support you cannot use.
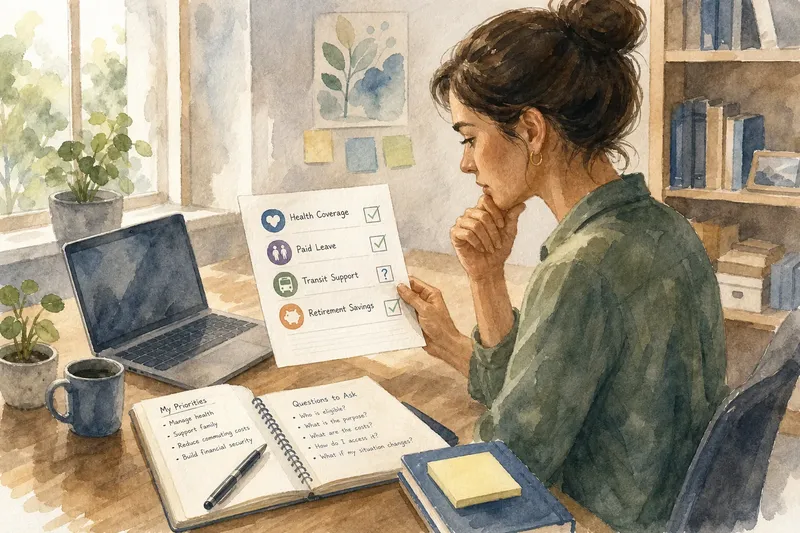
That does not mean the benefit is poorly designed or should be dismissed. Ask what it is for, who can use it, and whether its rules fit the problem you need to solve. Health coverage, paid leave, transit support, and retirement contributions serve different purposes, and their value can shift as your circumstances change.
Start with your need
People often compare benefits by label: paid leave sounds better than unpaid leave, for instance, and a broad health plan sounds better than a narrow one. Labels can hide the conditions that determine practical value. Timing, eligibility, access, costs, and available alternatives all matter.
Begin with the circumstance you want help with. Are you managing a recurring medical need, caring for a family member, getting to a worksite, building financial stability, or protecting time to recover? Naming the need helps you focus on relevant rules instead of attractive features that do not address your situation.
Imagine you have a long commute and are considering an employer transit benefit. If it covers the route and schedule you use, it may address a real expense. If you work remotely most days or travel when the covered service is unavailable, another benefit may fit better. The useful question is whether the details match your routine.
Match benefits to circumstances
Use your situation to sort available benefits. These categories can overlap, and the best fit may change after a move, a new caregiving responsibility, or a shift in work arrangements.
If care shapes your schedule
Look at leave, schedule flexibility, and caregiving support. Find out which events qualify, whether time away is paid, and how much notice is expected when plans change. A program may be hard to use if it covers only narrow circumstances or requires a schedule you cannot predict.
If a dependent-care account or reimbursement program is offered, ask which expenses qualify and when funds are available. Such programs may help with eligible costs, but they are not the same as flexible leave or assistance finding care. Decide which problem you need to solve before treating one as a substitute for another.
If you manage a health need
Focus on coverage, continuity, and access—not just the plan’s headline description. Ask whether your clinicians and medications are covered, how referrals work, and what costs you may face when you need care. If you expect treatment or regular prescriptions, the rules for those services may matter more than a feature you are unlikely to use.
Consider whether you can use the benefit at times and places that work for you. A counseling service, for example, may be less practical if appointment options conflict with your schedule. For decisions about treatment or coverage, consult a qualified health or benefits professional who can consider your circumstances.
If your budget is tight
Prioritize benefits that address a current pressure without creating a new one. A retirement contribution can support longer-term financial security, while paid leave can protect income during time away; neither necessarily solves an immediate cash-flow concern. Find out whether participation requires paycheck deductions, whether an employer contribution has conditions, and what happens if you leave the job.
A large-looking employer contribution is not automatically the best choice. The timing of access, any required employee contribution, and your immediate obligations all matter. If you are uncertain about tax or financial consequences, ask a qualified professional rather than relying on a general description.
If your work pattern varies
Check whether the benefit follows your actual work pattern. Transit support, meal programs, on-site services, and equipment allowances can depend on where and when you work. A benefit designed around a central office may have limited value if you are assigned to multiple sites or work remotely.
Ask whether you need advance approval, whether unused support can carry forward, and whether a schedule change affects access. A flexible option may fit better, or a modest benefit that reliably applies to your routine may be more useful.
If your needs are changing
Favor clarity and adaptability over a benefit that works only under one set of assumptions. A new caregiving role, a move, or a change in health can alter what matters. Find out when you can enroll, change an election, or request an accommodation, and what documentation or deadlines apply.
For a major change in circumstances, speak with the benefits team before making a decision that may be difficult to reverse. Ask for the rules in writing so you can compare them with your needs.
Questions about workplace benefits?
How can I tell what a benefit is meant to do?
Ask the benefits team to explain the program’s purpose and the need it is designed to address. Compare that purpose with your situation instead of assuming a familiar name tells the whole story.
What should I check before enrolling?
Check eligibility, enrollment timing, employee costs, access rules, and what happens if your employment or circumstances change. Ask for the plan document or policy, not only a brief summary.
Can I ask for a different arrangement?
You can ask whether another option, schedule, or accommodation is available, but the answer depends on the program and applicable rules. Explain the practical barrier you face and ask whom to contact about alternatives.
What if I cannot tell whether a benefit is worth using?
Separate the decision into two questions: does the benefit address a real need, and do its terms make it accessible to you? If either answer is unclear, request an explanation before you commit or plan around it.
Read the rules carefully
Once a benefit appears relevant, read the policy or plan information. A short workplace summary can omit exclusions, deadlines, approval requirements, or limits on who qualifies. Being eligible does not always mean you can use a benefit when you need it.
Use these checks to identify what you still need to know:
- Eligibility: Check whether job status, hours, location, length of service, or another condition determines who qualifies. If you meet the stated conditions, ask how to enroll; if not, ask whether another program applies.
- Enrollment timing: Check the enrollment window and which events allow a change outside it. If you are within the window, submit the required choice; if not, ask whether a qualifying event permits a change.
- Costs and commitments: Check paycheck deductions, required contributions, waiting periods, and time commitments. If they fit your budget and schedule, compare the benefit with your need; if they do not, ask about a lower-cost or more flexible option.
- Exclusions: Check which services, expenses, events, or situations are not covered. If your expected need is covered, confirm the access process; if it is excluded, ask the benefits team about another resource.
- Access: Check whether you need a referral, approval, form, provider, or advance notice. If you can complete those requirements in time, follow the stated process; if you cannot, ask what alternative route is available.
- Changing circumstances: Check whether a schedule, location, family-status, or employment change affects access. If coverage continues, keep the relevant policy; if it changes, ask when the change takes effect and what option replaces it.
Benefits are governed by plan documents, employer policies, and applicable local requirements. Check the relevant information before acting. If a benefit affects health coverage, taxes, legal rights, or a significant financial decision, seek advice from a qualified professional when needed.
Compare practical value
When you have more than one option, compare what each does for you in practice. A benefit may offer predictability, reduce a recurring expense, or give you time to handle a responsibility. Another may provide broader support but include conditions that make it harder to use. Your circumstances, not the label, determine which matters more.
Say you need time for recurring appointments. The policy allows leave, but its notice requirement is unclear. You check the policy and find that planned appointments require advance notice; you then ask the benefits representative how to handle appointments scheduled by a clinic on short notice. The resulting decision is clear: use the leave for appointments you can plan ahead, and ask about another option for those you cannot.
It is also reasonable to ask how benefits work together. Paid leave and flexible scheduling may address different parts of the same problem, while a reimbursement program and a health plan may have separate eligibility rules. Do not assume that using one makes you ineligible for another; ask how the programs interact.
Revisit the fit later
A benefit that suits you now may become less useful, and one you once ignored may become important. Revisit your choices when your work pattern or responsibilities change, and review enrollment materials when your employer allows adjustments. Keep copies of policy information and answers you receive so you can compare the rules over time.
When a benefit falls short, describe the obstacle precisely. “I cannot use this” is harder to address than “the service is available only during hours I am scheduled to work.” Ask whether another route exists, whether the rule can be clarified, or whether a separate resource is available. A clear question will not change every policy, but it can reveal options you might otherwise miss.
The myth of the one-size-fits-all workplace benefit fades when you compare its purpose with the life you actually lead. Treat a workplace benefit as an option to assess, not a promise of fit: check the rules, name the need, and ask the question that connects the two.